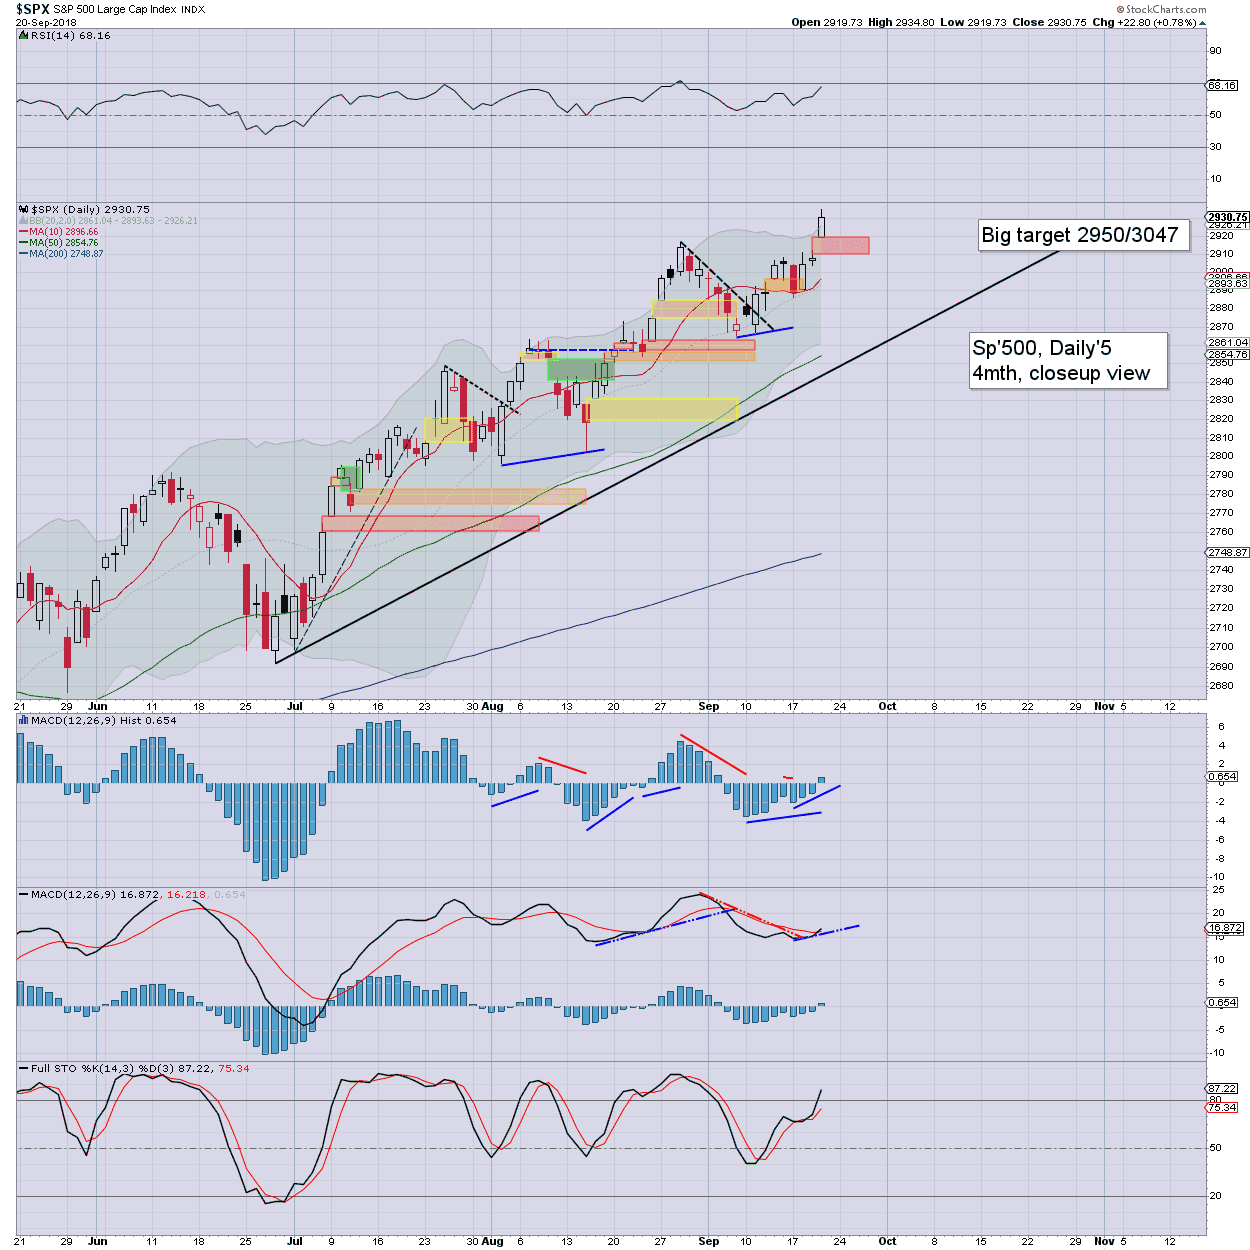
It was a mixed week for US equity indexes,
with net weekly changes ranging from +2.2%
(Dow), +1.4% (NYSE comp'), +0.8% (sp'500), -0.3% (Nasdaq comp', Trans), to
-0.5% (R2K). Near term outlook offers a little weakness, but broadly higher into year end.
Lets take our regular look at six of the main US indexes
sp'500
The sp' climbed for the 10th week of 12, settling +24pts (0.8%) at 2929, with a new historic high of 2940. A September settlement in the 2900s looks probable. The giant 3K threshold will be technically viable from mid October onward.
The key Fibonacci of 3047 won't be easy to clear, but with the Dow breaking above its direct equivalent of 26702, the sp' could be expected to follow. Any price action >3047 - if by mid November, would offer a year end ramp into the 3200s. The original year end target of 3245 is just about within range.
--
Nasdaq comp'
The Nasdaq comp' settled -0.3% at 7986. Underlying macd (blue bar histogram) threatens a bearish cross next week. First big support would be the 7600s, but considering the rest of the market, its difficult to see that.
Dow
The mighty Dow climbed for the 10th week of 12, settling higher by a very significant 588pts (2.2%) to 26743. The new historic high of 26769 was notably above the key Fibonacci of 26702, and it bodes well for the broader market into year end. The next fib' is 34430, which is 7687pts (28.7%) to the upside. I'll just add that the equivalent for the sp'500 is 3956.
NYSE comp'
The master index climbed for the 10th week of 12, settling +1.4% at 13236. New historic highs (>13637) are viable in October. The 14000s look on the menu before year end.
R2K
The R2K was the laggard this week, settling net lower by -0.5% to 1712. Underlying macd has turned negative for the first time since early August. The 1800s are realistic in Nov/Dec.
Trans
The 'old leader' - Transports, saw a net decline of -0.3% to 11532. This minor decline was ironically the biggest since late June. Higher WTIC/gasoline prices are clearly a downward pressure.
–
Summary
Three indexes were net higher, with three net lower for the week.
The Dow and sp'500 broke new historic highs.
The YTD market leaders of Nasdaq and R2K were the laggards this week.
YTD performance:
The Nasdaq continues to lead the way, currently +15.7%, with the R2K +11.5%, and the sp +9.6%. The Transports is +8.7%, the Dow is +8.2%, with the nyse comp' +3.3%.
--
Looking ahead
Key earnings; KBH, NKE (Tues'), CCL (Thurs')
The week will be focused on the Fed, as we're due the third rate hike of the year. How the bond market reacts will be especially important.
M -
T - Case-Shiller HPI, consumer con', Richmond Fed.
W - New home sales, EIA Pet' report.
FOMC: There will be an announcement at 2pm, that will detail a rate hike of 25bps to a new target range of 2.00-2.25%. Powell will host a press conf' at 2.30pm, and that will likely last an hour.
T - Weekly jobs, Durable goods orders, GDP (Q2, third estimate), intl' trade, pending home sales
F - Pers' income/outlays, Chicago PMI, consumer sent'.
--
If you value my work, subscribe to me.
For details:
https://permabeardoomster.blogspot.co.uk/p/subscriptions.html
Have a good weekend
--
*the next post on this page will likely appear 5pm EST on Monday.
Saturday, 22 September 2018
Thursday, 20 September 2018
The mighty Dow follows
US equity indexes closed broadly higher, sp +22pts (0.8%) at 2930. Dow
+251pts (0.9%) to 26657. Nasdaq comp' +1.0% to 8028. The two leaders -
Trans/R2K, settled u/c and +1.0% respectively. Near term outlook offers
choppy weakness into the Friday quad-opex.
sp'daily5
VIX'daily3
Summary
Suffice to add... new historic highs for the sp' and dow.
-
The mighty Dow follows
Some grand perspective.... Dow, monthly
A new historic high of 26697. The next key fib' is 26702 (the sp' equiv' is 3047). Upper bollinger is offering the 27200s in the near term.
--
Open day
Friday will be 'open day' at http://subscriber.permabeardoomster.com
First unlocked post will appear by 8.30am EST.
Goodnight from London
--
If you value my work, subscribe to me.
For details: https://permabeardoomster.blogspot.co.uk/p/subscriptions.html
Wednesday, 19 September 2018
Higher rates are bullish
US equity indexes closed moderately mixed, sp +3pts (0.1%) at 2907. The
two leaders - Trans/R2K, settled u/c and -0.4% respectively. VIX settled -8.1% to 11.75. Near term
outlook offers Thursday cooling, but likely no lower than around
2895/90.
sp'daily5
VIX'daily3
Summary
US equity indexes were pretty mixed today, with the Dow moderately higher, but with tech leaning somewhat weak. No new historic highs were seen, but they are clearly coming. Volatility was naturally subdued, with the VIX settling in the 11s. S/t outlook offers moderate equity weakness on Thursday, but likely no lower than the sp'2895/90 zone.
--
Higher rates are bullish
Yours truly has (vainly) tried for a few years to highlight something which the mainstream have long feared... higher interest rates/bond yields. The fed are clearly set to raise rates next week (+25bps to 2.00-2.25%), and also at the Dec'19th meeting.
Higher rates ARE inherently bullish for the US financials. Indeed, fears that the fed won't hike a third or fourth time this year, have been a drag on the financials since the early spring.
BAC, monthly
Today saw a bull flag provisionally confirmed. A push >33s is due, and that will offer the 38/40 zone, whether by year end (a stretch) or a more viable spring 2019. If I'm right, very bullish sector/main market implications into/across 2019.
--
--
Extra charts in AH (usually around 7pm EDT) @ https://twitter.com/permabear_uk
Goodnight from London
--
If you value my work, subscribe to me.
For details: https://permabeardoomster.blogspot.co.uk/p/subscriptions.html
sp'daily5
VIX'daily3
Summary
US equity indexes were pretty mixed today, with the Dow moderately higher, but with tech leaning somewhat weak. No new historic highs were seen, but they are clearly coming. Volatility was naturally subdued, with the VIX settling in the 11s. S/t outlook offers moderate equity weakness on Thursday, but likely no lower than the sp'2895/90 zone.
--
Higher rates are bullish
Yours truly has (vainly) tried for a few years to highlight something which the mainstream have long feared... higher interest rates/bond yields. The fed are clearly set to raise rates next week (+25bps to 2.00-2.25%), and also at the Dec'19th meeting.
Higher rates ARE inherently bullish for the US financials. Indeed, fears that the fed won't hike a third or fourth time this year, have been a drag on the financials since the early spring.
BAC, monthly
Today saw a bull flag provisionally confirmed. A push >33s is due, and that will offer the 38/40 zone, whether by year end (a stretch) or a more viable spring 2019. If I'm right, very bullish sector/main market implications into/across 2019.
--
| Summer has almost fully faded |
Extra charts in AH (usually around 7pm EDT) @ https://twitter.com/permabear_uk
Goodnight from London
--
If you value my work, subscribe to me.
For details: https://permabeardoomster.blogspot.co.uk/p/subscriptions.html
Subscribe to:
Posts (Atom)