Saturday, 9 July 2016

Set to break up and away

US equity indexes ended the week on a very positive note, sp +32pts @ 2129 (intra high 2131). The two leaders - Trans/R2K, settled higher by 2.5% and 2.4% respectively. VIX settled lower by -10.6% to 13.20. Near term outlook offers sp >2134 to new historic highs, with other indexes set to follow.


sp'daily


VIX'daily


Summary

With the jobs data pleasing Mr Market, equities built solid gains across the day. VIX was naturally crushed to the 13s... having now been cut in half from the BREXIT high.
--

re: the jobs data. So, May was revised to an even lower 11k net gain, whilst June is initially at 287k. Seriously, are the BLS using a random number generator lately?

Regardless, the market was pleased, and it made for a very bullish end to the week.
--


Market chatter from Schiff


--
sp'weekly


New historic highs look due

After a second consecutive net weekly gain, it would seem that rather than another failure, we'll see the sp'500 break a new historic high at next Monday's open - or at some point next week. The Dow and Nasdaq will duly follow, with the Trans/R2K set to take 3-6 months to also break new historic highs.

US equity Bears had their opportunity with the recent BREXIT vote, but failed to even attain a daily close under sp' 2K. The precious metals and US bonds continue to broadly climb, but that is not enough to negate the fact that the sp'500 is set to break above the May 2015 high.

So.. yes...  yours truly has waved the white flag.

Goodnight from London
--

*the weekend update will appear Sat' 12pm EST, and will detail the US monthly indexes
Friday, 8 July 2016

More bad news?

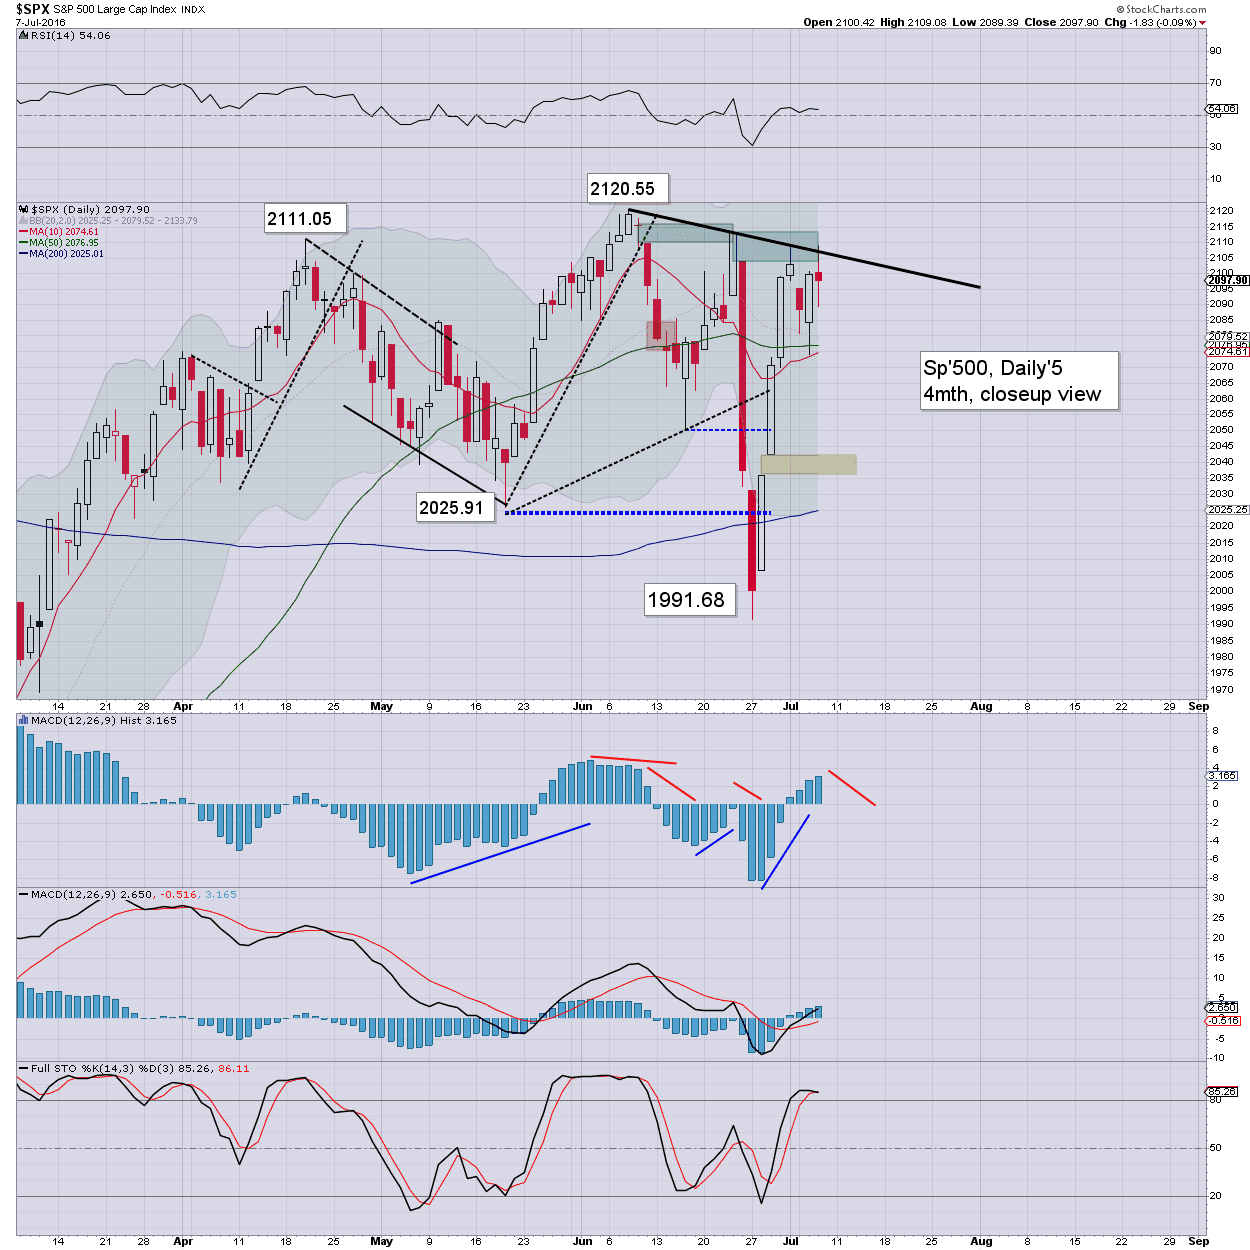
US equity indexes closed moderately mixed, sp -1pt at 2097 (intra high 2109). The two leaders - Trans/R2K, settled higher by 0.5% and 0.2% respectively. VIX settled -1.3% @ 14.76. Near term outlook continues to offer the 2040/30s, which should equate to VIX around the key 20 threshold.


sp'daily5


VIX'daily3


Summary

The morning high of sp'2109 was just another tease to those who still believe we're in a bull market. Arguably, today saw failure number 18, since the May 2015 high of 2134.


--
VIX remains relatively subdued, but as this afternoon showed, any degree of equity weakness will see the VIX jump pretty quickly.

From a pure cyclical perspective, equities are more likely to break lower.. than up and away.


--
More bad news?

The US capital markets await the latest employment data from the BLS. Regardless of whatever numbers are issued, what will matter is how the market interprets the data.

My guess is 90-110k net gains, but even if that is correct, would the market decide that 'bad news is bad news' or 'bad news is good news', in that a rate rise could be ruled out for the remainder of the year?

Anyway, besides the US data, the financial tremors continue to grow in the EU, and that can't just be dismissed as 'not important' by the equity bull maniacs.

notable weakness, DB, daily


A net daily decline of -3.2% to $12.56, but hey... its nothing to be worried about, right?

Goodnight from London

Thursday, 7 July 2016

Underlying financial tremors

US equity indexes closed moderately mixed, sp +11pts at 2099 (intra low 2074). The two leaders - Trans/R2K, settled -0.1% and +0.7% respectively. VIX settled -4.0% @ 14.96. Near term outlook continues to offer the 2040/30s - which should equate to VIX 19/20.


sp'daily5


VIX'daily3


Summary

It was not exactly the most exciting day in equity land, with a morning low of sp'2074, and then a pretty tedious (but not unexpected) latter day recovery to fill the price gap zone of 2095/2100.

VIX remains relatively subdued in the mid teens, a return to the key 20 threshold looks viable as early as this Friday.
--


The tremors are getting bigger

Far more notable than the past three days of main market price action, are the continuing developments for European financials. With stocks like DB and RBS continuing to implode, the stories of impending doom just keep on coming.

Mainstream chatter of a mass EU bank bail-in is increasing, as more recognise that huge capital injections are needed just to keep the EU system ticking over.

No doubt the ECB is standing by to print 'some number' of trillions to at least provide a temporarily fix. Further QE would be hyper-bullish for Gold and the related mining stocks.
-

For the systemic risk that remains the DB, it was just another day

DB, monthly, 20yr, linear scale


Nothing to add from yesterday's post on my 'fairvaluestocks' page.

--
The bigger weekly cycle continues to offer another big drop

sp'weekly1b


I've eyes on the MACD (blue bar histogram) cycle which is set to turn negative cycle in the near term. The pattern is similar to last December. First soft target is the 2000/1990 zone, and then the lower bollinger, which will be around 1990 next week.

As has been the case since summer 2015, the broader bearish outlook is dropped on any break >sp'2134, or for the less risk tolerant... >2113/20.
--

Fed/Market chatter from Schiff


--


As ever, I continue my intraday postings... see HERE for details.

permabeardoomster.com

Goodnight from London